U.S. Consumer Credit Education & Report Review Guidance
CROA & FCRA Compliant • Support: +1 (983) 212-7564
Consumer Credit Education & FCRA Dispute Guidance

Honest, No-Hype Credit Education & Report Review.

Facing report errors, unverified collections, or loan rejections? We review your reports line-by-line, educate you on your rights under federal law, and build a clear action plan — with zero false score promises.
See How It Works
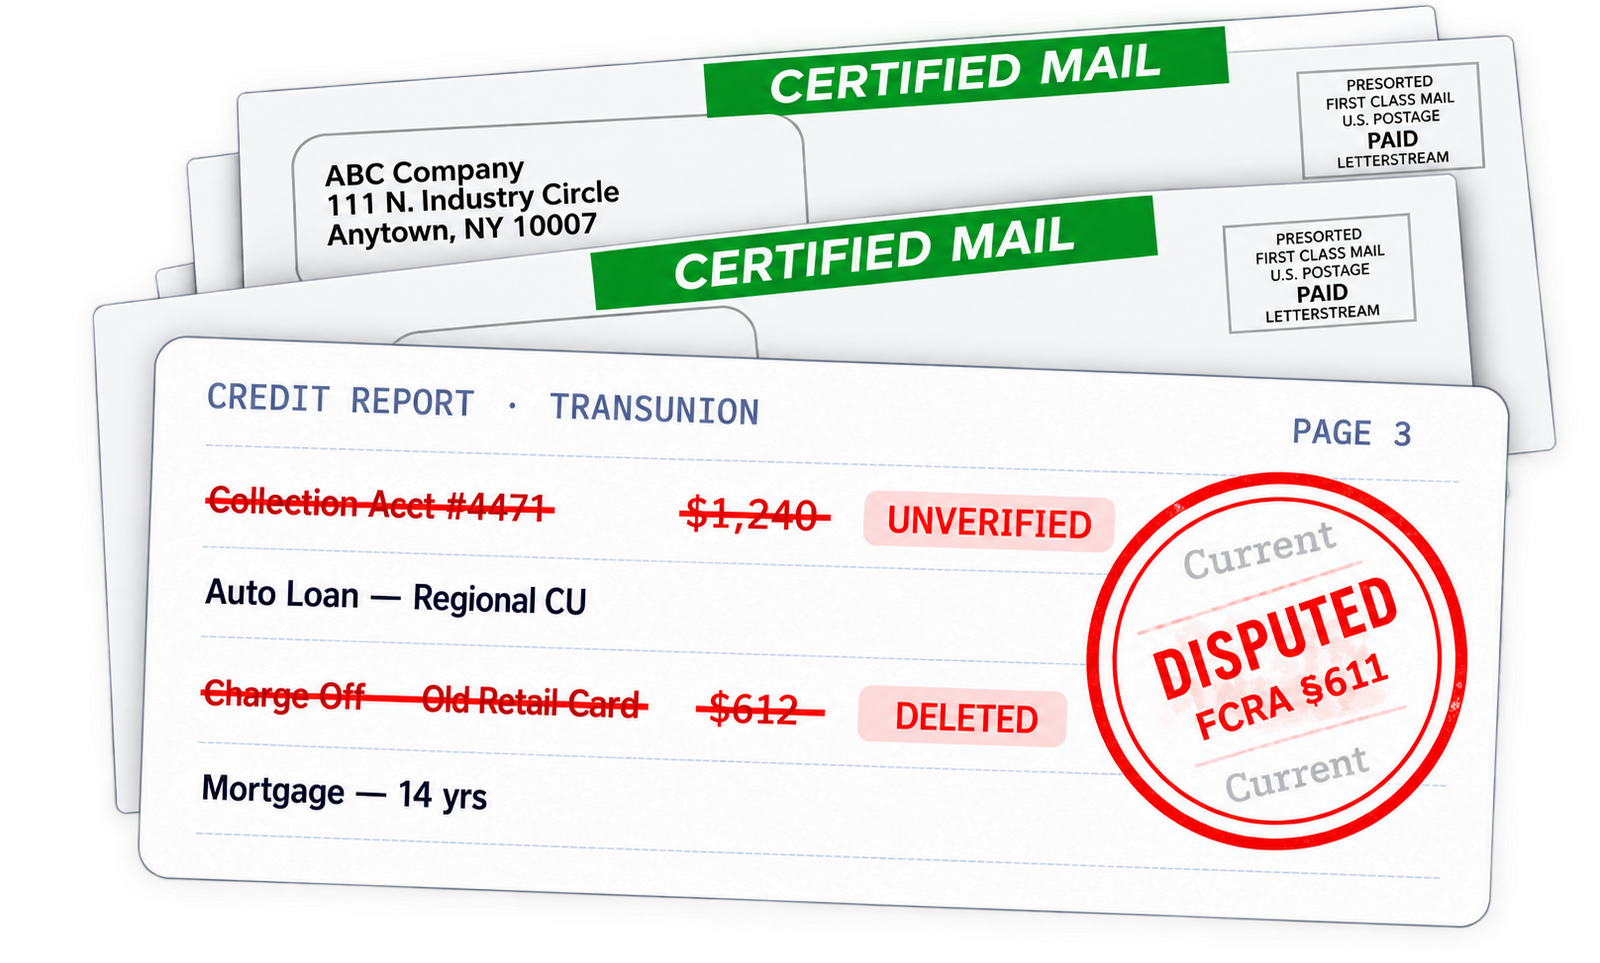
Credit dispute and certified mail illustration
FCRA & CROA Compliant
Strictly adheres to federal credit reporting and repair legislation.
Zero False Guarantees
We never promise illegal score spikes or deleting verified records.
100% Free Initial Review
No credit card needed, no hidden recurring fees, zero sales pressure.
Strict Confidentiality
No SSNs on public forms and we never sell your personal data.
Real Consumer Challenges

Credit Report Inaccuracies Are Common

According to the Federal Trade Commission, 1 in 5 consumers has a verified error on at least one report. Here are issues we audit and address most frequently:

Inaccurate & Zombie Collections
Third-party collection agencies often report accounts with incorrect balance figures, phantom fees, or accounts that were already resolved or passed the statutory 7-year reporting window.
Mixed Files & Bureau Misattributions
Credit bureaus frequently merge profiles of consumers with similar names, suffixes (Jr./Sr.), or close Social Security digits, saddling you with another person's delinquent accounts.
Duplicate Account Reporting
When an original debt is sold to debt buyers, both the original creditor and one or more collection entities may improperly report active derogatory balances simultaneously.
Charge-Off & Status Discrepancies
An account marked as "Charged-Off" may continue to report mounting late payments months after the charge-off date, or fail to reflect that the balance has been settled or satisfied in full.
Underwriting Red Flags for Mortgages
Mortgage and auto lenders look for specific derogatory markers like disputed accounts in underwriting, open disputed remarks, or recent 30-day lates that must be formally clarified.
High Utilization & Timing Confusion
Many consumers pay cards in full every month yet suffer lower scores because card issuers report balances on statement closing dates rather than due payment dates.
WHAT AI REVIEWS

Every Part of Your Credit Report.

From collections and charge-offs to personal information and inquiries, AI reviews your entire credit report — not just the obvious negative accounts.

SAMPLE LINE ITEM Duplicate / Unverified Collection
Midland Recovery Servicing
Reported Balance: $842
Original Debt: Paid to hospital in 2023
Agency Status: Open Collection
Federal Statutory Protection:
FCRA § 605 limits derogatory reporting strictly to 7 years from the Date of First Delinquency; FDCPA § 809 requires debt validation.
Frequently Documented Inaccuracies
  • Duplicate reporting: Both original creditor and collection agency reporting active balances.
  • Re-aged debts where the collection agency reset the 7-year statutory clock.
  • Medical debts under $500 or already paid medical debt (prohibited under CFPB rules).
Recommended Guidance Step

Request formal written debt validation and verify the original Date of First Delinquency (DOFD).

Transparent 4-Step Protocol

How We Work With You: Step by Step

No black boxes, no gimmicks. Just methodical examination of your rights, documented evidence, and strict compliance with federal laws.

01 30–45 Mins
Confidential Report Audit
We guide you on obtaining your authentic free annual reports from Equifax, Experian, and TransUnion via AnnualCreditReport.com and conduct a line-by-line audit.
Deliverable: Categorized summary of verified errors, violations, and valid items.
02 1–2 Days
Clear Rights & Strategy
We separate what can legally be questioned from what must be managed through responsible financial habits. We never mislead you into disputing valid debts.
Deliverable: Personalized dispute strategy roadmap citing applicable FCRA sections.
03 30-Day Window
Formal Documentation
We assist in drafting factual, evidence-backed dispute packages directly to credit bureaus and furnishers, strictly tracking statutory 30-day investigation windows.
Deliverable: Custom consumer dispute letters with USPS certified mail checklists.
04 Ongoing
Rebuilding Education
Credit repair alone does not create a strong score. We educate you on trade line seasoning, credit mix, utilization control, and safe rebuilding options.
Deliverable: Sustainable 12-month credit wellness blueprint for financial independence.
Reminder of Federal Law: You have the legal right to dispute inaccuracies in your credit report directly with credit bureaus and furnishers on your own at any time for free.
Zero Obligation • 100% Anonymous

Confidential Credit Health Self-Check

Answer 3 quick questions to receive a personalized roadmap of your legal rights and document preparation steps.

1. When was the last time you pulled your official 3-bureau credit reports?
The Transparency Standard

What We Do vs. What We NEVER Do

Federal law strictly protects consumers from deceptive credit practices. We believe in total upfront honesty.

← Swipe sideways to view full comparison →
Subject Area
What We Do
What We Never Do
Score Guarantees
Honest Truth: We explain how scoring models work. Federal law prohibits guaranteeing any score outcome.
Never promise bogus claims like "+100 points in 30 days" or guarantee specific score increases.
Accurate Negative Records
Educate you on how accurate negative items age and how their impact diminishes over time, focusing on positive trade line rebuilding.
Never promise to erase legitimate, verified debts or truthful negative records that comply with the 7-year rule.
Upfront Retainers
100% free initial consultation. If you choose our guided drafting service, billing is strictly compliant with CROA guidelines.
Never demand large upfront retainer fees before any actual consultation or document review takes place.
Identity & CPN Advice
We only work with your legitimate personal credit file and lawful consumer rights under federal and state regulations.
Never advise using "Credit Privacy Numbers" (CPNs), file segregation, or new EINs (which is federal bank fraud).
Dispute Methods
Draft customized, factual, evidence-based dispute communications tailored to the exact reporting error in your file.
Never send spammy computer-generated form letters that credit bureaus immediately flag and discard as frivolous.

Frequently Asked Questions

Straightforward answers about our services, federal rights, and the credit reporting system.

No — and you should immediately distrust any organization that claims they can. Under the Credit Repair Organizations Act (CROA, 15 U.S.C. § 1679b), it is explicitly illegal for any credit assistance entity to make untrue or misleading representations about what services can achieve. We help identify verifiable reporting errors and assert statutory rights under federal law.
No legal credit guidance company can force the removal of accurate, timely negative information. Under the FCRA, negative records that are accurate may legally remain for up to 7 years from the date of first delinquency (10 years for Chapter 7 bankruptcy). What CAN be corrected are items that are inaccurate, incomplete, duplicate, out-of-date, or unverifiable.
Yes, absolutely! Federal law gives every consumer the right to dispute inaccurate information directly with credit bureaus (Equifax, Experian, TransUnion) and data furnishers at no cost whatsoever. Our guidance service exists for consumers who want experienced assistance spotting subtle violations and drafting formal legal communications.
Under FCRA § 611, credit reporting agencies are required by federal law to conduct a reasonable investigation and provide written results within 30 calendar days of receiving your dispute. If the furnisher fails to verify the disputed item within this statutory window, the bureau must delete or correct the record.
The only official, government-authorized website to obtain free credit reports from Equifax, Experian, and TransUnion is www.AnnualCreditReport.com. All three bureaus currently offer free weekly online report access. You never need to enter a credit card or pay monthly subscriptions.

Book Your Free Credit Report Consultation

Speak with an experienced credit guidance specialist. No pressure, no obligations, and 100% confidential.

Please enter your full name.
Please enter a valid email address.
Please enter a valid phone number.
Please select your preferred time.
Your privacy matters. Please do not submit sensitive information such as your Social Security number, bank account details, credit card information, or passwords through this form.
100% Confidential • No Credit Card • CROA Compliant

Book Free Consultation

Client Lead Form • 123creditfree.com
Loading client lead form...

Book a Consultation

Calendar Booking • 123creditfree.com
Loading booking calendar...